How Exterior Maintenance Impacts Home Inspection and Insurance Ratings
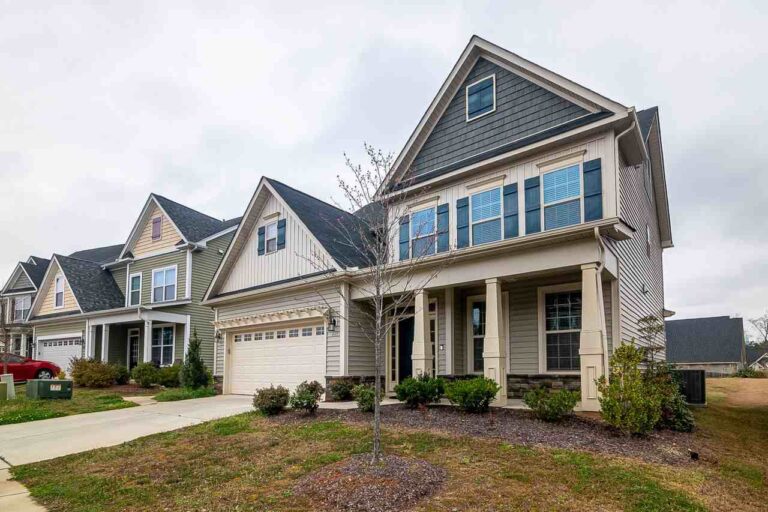
When homeowners think about maintaining their property, curb appeal is usually top of mind. But the condition of a home’s exterior does more than influence how a house looks from the street — it plays a direct role in how the home performs during an inspection and how it’s rated for insurance purposes.
Peeling paint, aging siding, a worn roof, or neglected trim aren’t just cosmetic issues. They’re signals that inspectors and insurers use to assess risk, and they can end up affecting coverage options, premiums, and even a home’s resale value.
Understanding this connection can help homeowners prioritize maintenance projects that protect both the structure of their home and their financial standing.
Why Exterior Condition Matters to Inspectors
A home inspection is meant to give buyers, sellers, and insurers an honest picture of a property’s condition. Inspectors are trained to look past surface-level appearances, but exterior wear is often the first clue that deeper problems may exist underneath.
For example, cracked or peeling paint on siding, trim, or fascia boards can indicate that moisture has been getting past the protective coating for some time. Once water intrusion becomes a possibility, an inspector will look more closely at:
- Wood rot in siding, soffits, and trim
- Mold or mildew growth in shaded or poorly ventilated areas
- Foundation cracks that may be allowing water to seep in near the base of the home
- Roof wear, including missing shingles, granule loss, or soft spots in the decking
- Window and door seals that may have failed, allowing air and water infiltration
None of these issues are guaranteed just because paint is peeling, but exterior deterioration is often the visible tip of a larger maintenance iceberg. Inspectors document what they see, and that documentation becomes part of the record buyers and insurers rely on.
How Insurers Use Exterior Condition to Assess Risk
Insurance companies aren’t in the business of guessing. When they evaluate a home for a new policy or a renewal, they’re estimating the likelihood of a future claim. A well-maintained exterior suggests a homeowner who stays ahead of small problems before they become expensive ones. A neglected exterior suggests the opposite.
Some of the exterior factors insurers commonly weigh include:
| Exterior Feature | What Insurers Look For | Why It Matters |
| Roof condition | Age, missing shingles, sagging areas | Roofs are the leading cause of weather-related claims |
| Siding and paint | Peeling, cracking, or exposed wood | Signals possible moisture intrusion and rot |
| Gutters and drainage | Clogs, disconnected downspouts | Poor drainage contributes to foundation and basement issues |
| Trees and landscaping | Overhanging limbs, root proximity to structure | Storm damage and foundation risk |
| Windows and doors | Cracked seals, visible gaps | Water and pest entry points |
This is why some insurers request exterior photos or a inspection contingency before finalizing a policy, particularly in regions prone to severe weather. A home with visible exterior neglect may be flagged for a more detailed review, which can slow down underwriting or lead to higher premiums to offset the perceived risk.
Regional Weather Adds Another Layer
In states with high humidity, heavy storm seasons, or hurricane exposure, exterior maintenance carries even more weight. Homes in these climates face faster paint degradation, quicker wood rot, and more frequent roof stress from wind and rain. Insurers operating in these markets often build regional risk factors into their underwriting models, since claims related to storm damage, water intrusion, and wind-related roof loss tend to cluster geographically.
This is one reason coverage terms can vary so much by state. Florida Home Insurance, for instance, often accounts for hurricane exposure and humidity-driven wear in ways that a policy written for a drier, milder climate wouldn’t need to.
Maintenance Habits That Support Better Inspection and Insurance Outcomes
The good news is that most of the issues inspectors and insurers care about are preventable with routine upkeep. Homeowners don’t need to overhaul their entire exterior every year — they simply need a consistent maintenance rhythm.
A few habits that tend to make the biggest difference:
- Repaint or reseal exterior surfaces before coatings fully fail, rather than after wood is already exposed
- Inspect the roof annually, especially after major storms, and address minor damage before it spreads
- Clean gutters and downspouts at least twice a year to keep water moving away from the foundation
- Trim trees and shrubs away from the roofline and siding to reduce moisture retention and storm damage risk
- Check caulking and seals around windows and doors annually
- Address small cracks or gaps in siding or trim promptly, before moisture has a chance to get behind the surface
Keeping a simple log of when these tasks were last completed can also be useful. If an insurer or inspector asks about maintenance history, having dates and, ideally, photos on hand can support a smoother review process.
The Bigger Picture
Exterior maintenance isn’t just about appearances — it’s a practical part of protecting a home’s long-term value and keeping insurance costs predictable. Inspectors use visible wear as a starting point for deeper evaluation, and insurers factor exterior condition into how they assess risk and set terms.
Staying consistent with upkeep, understanding regional risk factors, and knowing what documentation might be helpful during underwriting can all contribute to a smoother experience, whether a homeowner is buying, selling, or simply renewing a policy.
Every insurer weighs these factors a little differently, which is why it’s worth asking directly how exterior condition affects your own policy. Companies like Worth Insurance are one example of an insurer that factors regional and structural risk into how they evaluate a home.